BRITISH COLUMBIA · MORTGAGE BROKERAGES
BC Mortgage Brokerage E&O: The Document Check After October 13
A practical document review for BC mortgage brokerages and their insurance brokers, with the effective date and original BCFSA requirements clearly identified.
The requirement now in effect
BCFSA Statement 26-007, published March 31, took effect October 13, 2026. It concerns BC mortgage brokerages licensed under the Mortgage Services Act, rather than every Canadian insurance customer. It requires E&O extended to fraudulent acts: at least $500,000 per occurrence and $1 million across a 365-day period. It also specifies a three-year reporting tail after the listed closure or licence events, coverage for licensed service categories, separate coverage for each brokerage and protection of provincial minimums from claims elsewhere. Read the statement for its exact scope and conditions. [1]
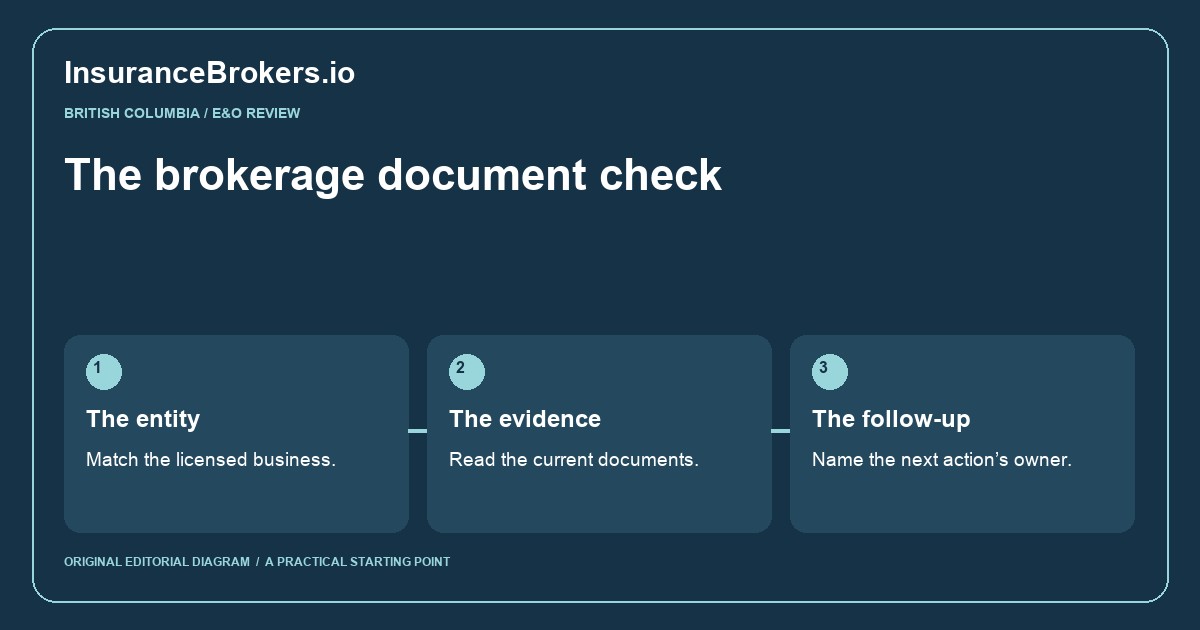
Start with the legal entity
Put the brokerage’s current licensed name beside the policy schedule. Review trading names and related entities separately. A familiar group name on a document does not answer which licensed business holds the coverage. Record a mismatch as an open question for the insurer or licensed insurance broker; do not silently amend the document yourself.
Read the documents together
Gather the schedule, policy wording, endorsements and renewal information in one controlled file. Give each document a date and version so reviewers can distinguish a current endorsement from an old quotation. Write down who supplied it and which question it answers. This is a proposed working method, not a declaration that a document package meets the rules.
Give each unresolved point an owner
Ask the insurance professional to identify the wording relevant to the requirements. For example, which document addresses the licensed services, and what arrangements apply if the brokerage’s structure changes? Avoid accepting a general description where the question concerns a particular entity or policy term. Keep the answer with its source document and follow-up date.
Keep the notification questions visible
BCFSA requires immediate notice when E&O is cancelled or not renewed, falls below the minimum, or a claim is made. It identifies IRIS for notifications. Insurance amendments must be submitted within 30 days. Consult the statement for the specified amendment details. [1]
Use a review record that another person can follow
A useful record says what was checked, what evidence was used, what remains unanswered and who takes the next action. It should help a successor continue the work without reconstructing an email trail. Keep confidential policy and claim details in the brokerage’s own controlled records; this public checklist does not collect them.
The next conversation
Bring unresolved wording and entity questions to the brokerage’s licensed insurance broker or insurer. Questions about the regulatory requirement belong with BCFSA. This guide helps organise that conversation; it does not certify a policy or replace the original statement. For a different property-management topic, see our BC strata winter responsibilities checklist.
Source and date check
[1] BCFSA, Mortgage Brokerage Insurance Requirements, Statement 26-007. Published March 31, 2026; effective October 13, 2026; checked October 23, 2026. Regulatory facts are attributed to that statement. The document-review workflow is original editorial commentary.